
Perpetual Futures Explained: Funding Rates, Leverage, and Liquidation


Perpetual futures have no fixed expiry date, but how long you can maintain a position still depends on margin, funding, and platform rules. The margin you commit does not define the full amount of your price exposure, and an unrealized gain on screen is not the same as net profit you can ultimately withdraw. To understand these products, follow one position: calculate notional value and initial margin, check price changes, funding payments, and closing fees, then examine liquidation conditions if the market moves against you. Each amount serves a different purpose, so leverage alone cannot tell you the risk.
Key Takeaways
- Notional value measures price exposure; margin is the capital supporting that position.
- With position size unchanged, increasing leverage does not directly increase price P&L.
- The mark price is a risk reference, not a price at which execution is guaranteed.
- Calculate funding and trading fees separately, then combine them into net position P&L.
- No fixed expiry does not mean you can safely maintain a position indefinitely.
What Keeps Perpetual Futures Working Without an Expiry Date?
Perpetual futures are derivatives without a fixed expiry date. They typically use a funding mechanism to help keep contract prices close to a spot reference price. You can open long or short positions and take exposure to the corresponding price direction. A position does not automatically end because a scheduled delivery date arrives, but it must continue to meet margin and other product requirements. “Perpetual” describes the contract's term, not a promise of position safety.
An ordinary, unborrowed spot purchase gives you the underlying asset. A perpetual futures position gives you the price exposure defined by the contract. Going long contracts representing 0.1 BTC does not add 0.1 BTC to your wallet for withdrawal. Dated futures have their own expiry and settlement arrangements; the fact that both products use margin does not make their holding conditions identical.
Funding is central to understanding perpetual pricing. A common mechanism transfers payments between long and short holders according to specified rules. By changing the cost of holding positions, it influences demand and helps constrain deviations between the contract price and the spot reference. It does not guarantee that the two prices always match. Short-term supply and demand, liquidity, and market volatility can still create a gap.
No fixed expiry also does not mean a platform will maintain a product forever. You may close a position voluntarily, it may be liquidated for insufficient margin, or it may be affected by contract termination or other rule-based arrangements. Funding does not eliminate platform or counterparty risk either.
The calculations below use a USDT-settled linear BTC perpetual contract throughout. All prices, leverage settings, rates, and margin parameters are educational assumptions, not live market data or quotes from any platform. Coin-margined inverse contracts use different pricing and settlement methods, so the same formulas cannot simply be applied to them.
How Much Margin Does a 6,000 USDT Position Require?
For an opening notional value of 6,000 USDT at 5× leverage, the simplified initial margin is 1,200 USDT. This amount supports the position; it is neither the purchase price of the equivalent spot asset nor a trading fee. Actual order requirements may include fee reserves, and not all available account funds may be usable for that order. The simplified figure should therefore not be treated as a minimum deposit requirement.
Start with one long position that will be used throughout the example:
| Item | Example assumption and calculation |
|---|---|
| Contract type | USDT-settled linear BTC perpetual |
| Direction and size | Long contracts representing 0.1 BTC |
| Average entry execution price | 60,000 USDT |
| Opening notional value | 0.1 × 60,000 = 6,000 USDT |
| Leverage setting | 5× |
| Simplified initial margin | 6,000 ÷ 5 = 1,200 USDT |
| Margin mode | Isolated, with automatic margin replenishment disabled |
| Assumed opening trading fee | 6,000 × 0.05% = 3 USDT, reserved separately |
The 0.1 BTC figure already expresses the position in units of the underlying asset. If an order interface uses a number of contracts, first check how much each contract represents. Do not treat the contract count as a BTC quantity. An incorrect unit will distort notional value, margin, and P&L together.
Keep the comparison consistent when examining leverage and price P&L. If you retain this 0.1 BTC position and change only the leverage to 10×, simplified initial margin falls to 600 USDT. However, every 1,000 USDT move in BTC still changes price P&L by 100 USDT. The same loss represents a larger share of margin and leaves a thinner buffer; the price P&L has not doubled by itself.
A different situation arises if you keep 1,200 USDT of margin but use higher leverage to increase the position size. Notional exposure then grows, and the same price move produces a larger change in P&L. When comparing risk, write down quantity, notional value, and allocated margin together rather than comparing only “5×” and “10×” on screen.
The opening 6,000 USDT is not a permanently fixed position value either. With quantity held at 0.1 BTC, current notional value changes as the reference price moves. That matters directly for subsequent funding and maintenance margin calculations.
What Do Mark Price, Last Traded Price, and Actual Execution Price Tell You?
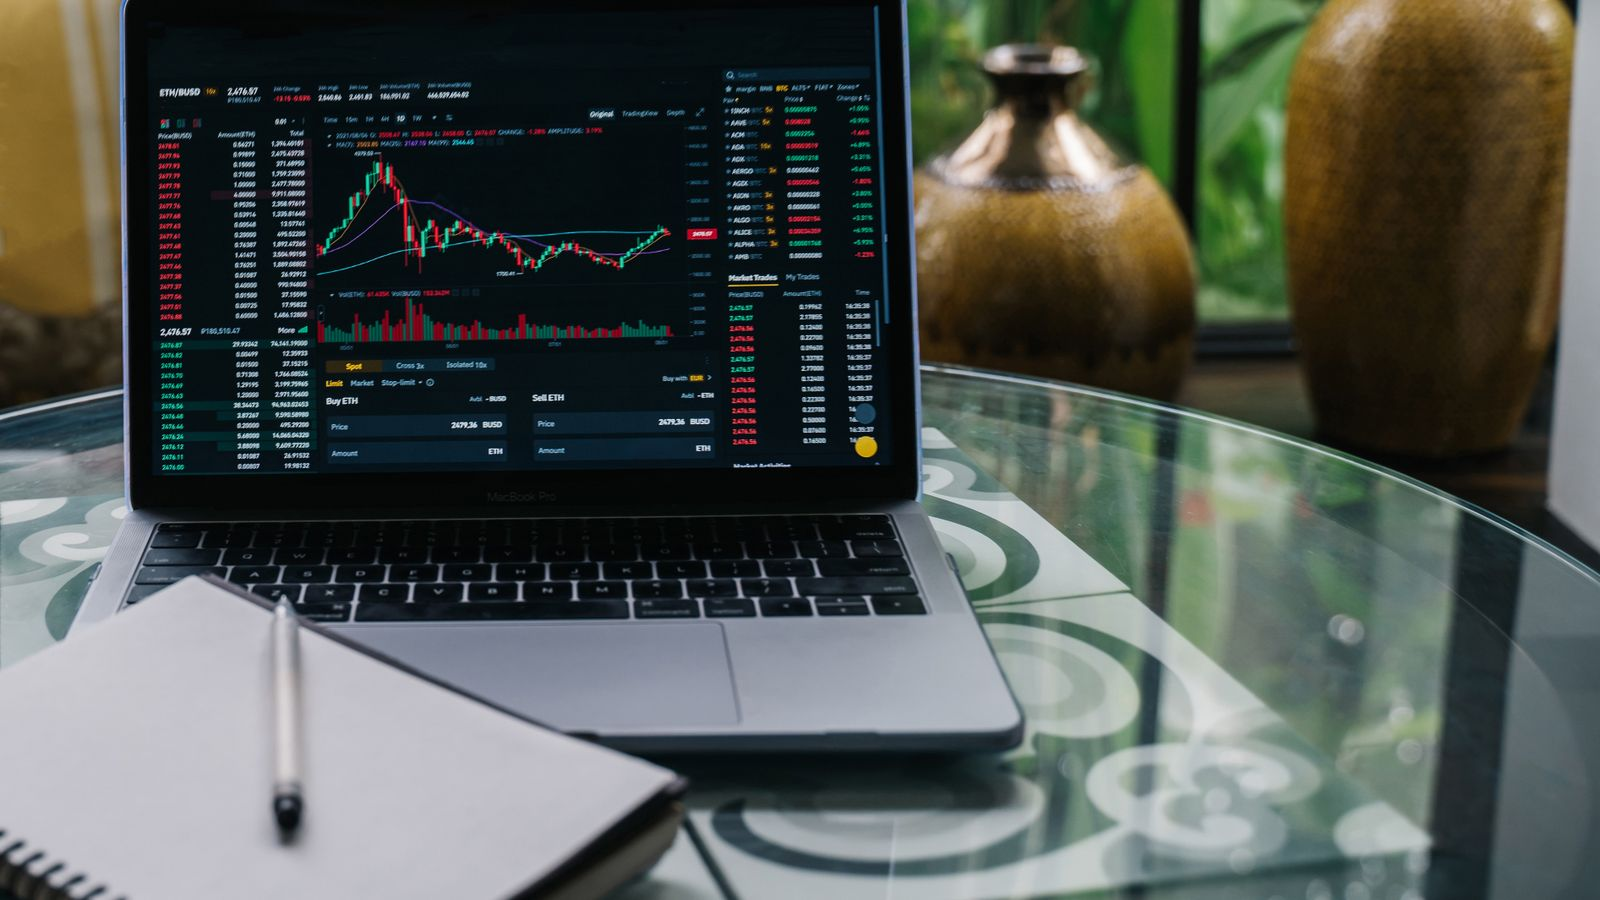
To assess position risk and calculate actual results, distinguish what each price is used for. The mark price is a risk reference calculated under the platform's rules. The last traded price is the price of the most recent market trade. Your average execution price comes from how your own order fills. These can differ: a risk reference is not a guaranteed exit quote, and a default candlestick chart alone cannot show your distance from liquidation reliably.
Mark Price Is a Risk Reference, Not an Exit Quote
An index price is generally constructed from spot market data according to platform rules. A mark price is calculated using relevant references and the contract's methodology, and is commonly used for margin risk, liquidation assessment, and some P&L displays. Algorithms and procedures for abnormal markets vary by product; there is no single fixed formula used by every platform.
Suppose that while you hold the example position, the mark price is 61,000 USDT and the last traded price is 61,020 USDT. The 20 USDT gap does not by itself indicate an error. The prices serve different purposes. Even if the latest trade took place at 61,020, you may not be able to sell the entire position at that price. Bid depth, order type, and the execution process still matter.
When reviewing the position interface, check whether unrealized P&L uses the mark price or last traded price, and which reference applies to liquidation. If fields show different amounts, examine their calculation methods before treating the difference as a fee or an actual loss.
Calculate Price P&L for the Same Position
For this linear long, unrealized price P&L estimated using the mark price equals quantity multiplied by the price difference. Therefore, 0.1 × (61,000 − 60,000) = 100 USDT. If a display instead uses the 61,020 USDT last traded price, it shows 102 USDT. Neither figure is the final net profit from closing the position.
Do not multiply this price P&L by 5× leverage again: the 0.1 BTC quantity already expresses the exposure. A short uses the opposite price difference—quantity multiplied by entry price minus reference price. When you actually close, replace the reference with your average execution price and account for fees. Further price movements can increase the unrealized gain, reduce it, or turn it into a loss.
How Is Funding Paid or Received, and How Does It Affect Holding Costs?
Funding generally consists of payments exchanged between long and short position holders under specified rules. It is separate from the trading fee charged when an order executes. Under a common arrangement, longs pay shorts when the rate is positive, and the direction reverses when it is negative. Funding helps influence the pricing relationship between contracts and spot assets, but it is not equivalent to interest on a spot-market loan from the platform.
For example, Bybit's funding calculation for USDT linear contracts applies the relevant rate to the position value at settlement. Retain the original long and assume you hold it through one funding settlement. If the mark price is 61,000 USDT and the rate for that settlement is +0.01%:
Funding payment = 0.1 × 61,000 × 0.01% = 0.61 USDT.
The long pays 0.61 USDT on this occasion. The calculation uses the current 6,100 USDT position value, not the 1,200 USDT initial margin or a permanently fixed opening notional of 6,000 USDT. Even if quantity remains unchanged, a different price can change the calculation base at the next settlement.
Read the percentage rate together with its settlement interval. Contracts may use different intervals, and some platforms adjust frequencies or rate limits. Funding should not universally be described as occurring every eight hours. An estimated rate on screen may also differ from the final settled rate, so check the settlement record. Inclusion in a particular payment depends on actual position eligibility and settlement rules. Submitting a closing order near settlement does not necessarily mean you have exited that funding cycle.
If you continue holding, record the actual amount paid or received each time rather than mechanically converting one 0.61 USDT payment into an annual cost. Payment direction, rates, and position size can all change. Receiving funding also does not make the whole position profitable: price losses may exceed the funding income.
Where the payment is deducted matters for the risk buffer. For example, some platforms use available balance first and deduct from position margin if that balance is insufficient. In that situation, funding can increase liquidation risk. Deduct each actual cost only once when calculating net P&L, and use the platform's actual deduction method when checking margin. Avoid mixing wallet balance with position margin.
How Do You Calculate Final Net P&L from Entry to Exit?
The final result should combine price P&L from actual executions with funding received, less funding paid and applicable trading fees. An earlier unrealized gain is only an estimate at a particular moment, and released margin is not newly earned money. For this position, reconcile the opening trade, the single funding settlement, and the full close in one set of records.
Assume you close the entire position after that funding settlement at an average execution price of 62,000 USDT, without holding through another funding time. Also assume opening and closing trading fee rates are both 0.05%, with no other charges. The result is:
| Item | Calculation | Effect on net P&L |
|---|---|---|
| Price P&L | 0.1 × (62,000 − 60,000) | +200 USDT |
| Opening trading fee | 6,000 × 0.05% | −3 USDT |
| Funding paid | 6,100 × 0.01% | −0.61 USDT |
| Closing trading fee | 6,200 × 0.05% | −3.10 USDT |
| Net P&L | 200 − 3 − 0.61 − 3.10 | +193.29 USDT |
USDT contract P&L calculations distinguish price P&L from the result after fees. Here, 200 USDT is the price gain; 193.29 USDT is the net gain after the assumed costs. Opening and closing trade values differ, so the fee amounts differ even with the same rate. Neither side should simply be calculated on the margin amount.
Because this calculation already uses actual average execution prices, spreads or slippage reflected in those prices should not be deducted again as the same cost. To assess execution quality, you can separately compare expected prices with average fills, identifying the benchmark you use. Actual trading fees also depend on the rate at execution, the order's role, and any applicable adjustments. The example rate is not a platform commitment.
If you add to the position, reduce it, or receive several fills, update the calculation using actual quantities and execution records, and aggregate funding payments individually. When reconciling changes in account assets, separate deposits, withdrawals, and other positions. An increase in account balance may not come entirely from this trade, and returned margin must not be counted again as profit.
Why Can Liquidation Happen Before All Your Margin Is Lost?
Liquidation generally depends on whether margin equity continues to meet maintenance requirements. The process does not necessarily wait until all margin is lost. Initial margin addresses entry requirements, while maintenance margin governs continued holding. Adverse price movements, fee deductions, or other account factors can leave insufficient equity supporting the position. Having no expiry does not allow a position to bypass that risk threshold.
Maintenance Margin Sets a Minimum for Keeping the Position Open
Consider an alternative adverse-price scenario for the original 0.1 BTC long, separate from the profitable exit above. If the mark price falls from 60,000 to 54,000 USDT, the unrealized price loss is 600 USDT—half the 1,200 USDT initial margin. A 10% decline in the underlying price does not mean margin falls by only 10%. Actual remaining equity also depends on costs and where they are deducted.
Take a further static calculation. Assume a maintenance margin rate of 0.5% and temporarily ignore other fees and funding. At a price of 48,200 USDT, simplified equity is 1,200 − 1,180 = 20 USDT, while the maintenance requirement is 4,820 × 0.5% = 24.10 USDT. Equity is still above zero but is already insufficient. This illustrates the principle only; it does not mean the position could actually remain open until that price. The platform may trigger action earlier.
For example, Bybit's isolated-margin liquidation process uses the mark price as the trigger reference and may involve order cancellation, partial reduction, or full closure. Actual thresholds also depend on risk tiers, fee reserves, and other rules. “Liquidation happens only after an adverse move of 1 ÷ leverage” is therefore not an accurate formula, and the trigger reference does not guarantee the final liquidation outcome or price.
How Do Isolated Margin, Cross Margin, and Stop-Losses Differ?
Isolated margin generally manages risk using margin allocated to a position. Cross margin may draw support from a broader pool of eligible account assets, making other positions' P&L and collateral values relevant to risk. Automatic margin replenishment changes the amount of capital actually committed. Adding margin can change the buffer but does not erase an existing loss; reducing position size changes subsequent price exposure.
Check the trigger reference for a stop-loss too. If a stop uses the last traded price while liquidation uses the mark price, they may be reached at different times. Even after a stop triggers, execution at the specified price is not guaranteed. If a bot runs a DCA or grid strategy, distinguish spot arrangements from futures arrangements. Automated orders do not remove margin or funding requirements.
If you manage relevant crypto assets with Biya, use this position ledger as a framework when comparing available products: check quantity, margin mode, price references, and exit conditions separately. Reconcile the Biya fee center with actual orders to establish charges for the relevant product, rather than applying stock or spot rates to perpetual futures. A lower individual trading fee cannot replace an assessment of funding and liquidation risk. Before continuing to hold, understand which funds support the position and how you plan to exit. Service availability depends on your location, identity verification results, platform rules, and applicable laws and regulations.
Frequently Asked Questions
Can a perpetual futures position be liquidated at 1× leverage?
Yes. A 1× setting alone does not establish that liquidation is impossible. Check the contract type, margin equity, maintenance requirements, costs, and account mode. Changes in collateral value or funding deductions can also affect the buffer. The applicable contract and platform risk rules determine the specific conditions.
Does a positive perpetual funding rate mean the price will rise?
No. A positive rate is not a reliable prediction of rising prices. Under a common mechanism, it means longs pay funding to shorts and reflects related pricing and positioning conditions. Prices can still fall, and funding direction and levels can change. Assess price exposure and holding costs separately.
Why can a perpetual position lose money when the price barely changes?
Funding and trading fees can make the net result negative even when prices move little. Actual average entry and exit prices may also differ from the market prices you observed. Funding can be income or an expense, so calculate the result from actual payment and execution records rather than judging only whether the chart moved sideways.
Why can a perpetual position be liquidated before its stop-loss executes?
A stop-loss and liquidation may use different price references, allowing the mark price to reach the liquidation threshold first. A triggered stop also still needs to execute, and market depth, price jumps, and order settings can affect the outcome. Check trigger settings and allow a risk buffer; a stop-loss does not guarantee execution.
Does lowering leverage after opening a perpetual position reduce an existing loss?
It does not directly reduce an existing price loss. If quantity and price are unchanged, changing the leverage setting does not erase the P&L amount. Lower leverage may require more margin. Whether an adjustment is allowed, how much additional capital is needed, and how the liquidation reference changes depend on account rules.
Can coin-margined perpetuals use the same P&L formula as USDT contracts?
Not directly; distinguishing linear and inverse contracts is especially important. Some coin-margined inverse products use reciprocal prices and settle in the underlying coin. Changes in the collateral's own price also affect risk. Confirm the contract multiplier, quote asset, and settlement asset before calculating P&L and margin.
*This article is provided for general information purposes and does not constitute legal, tax or other professional advice from BiyaPay or its subsidiaries and its affiliates, and it is not intended as a substitute for obtaining advice from a financial advisor or any other professional.
We make no representations, warranties or warranties, express or implied, as to the accuracy, completeness or timeliness of the contents of this publication.
Related Blogs of
Brokerage Fees vs. Commissions: Key Differences and Total Trading Costs
Frost Bank Currency Exchange: Fees, Supported Currencies, and Non-Customer Requirements

Intesa Sanpaolo Wire Transfer Fees to the US: Charges, Exchange Rates, and Total Cost

Offline Digital Wallets Explained: Payments Without Internet and Their Limits

Choose Country or Region to Read Local Blog
 Australia
 Austria
 Belgium
 Canada
 Cyprus
 Czech Republic
 Denmark
 Estonia
 Finland
 France
 Germany
 Greece
 Hong Kong
 India
 Indonesia
 Ireland
 Italy
 Japan
 Latvia
 Lithuania
 Luxembourg
 Malaysia
 Malta
 Morocco
 Nepal
 Netherlands
 New Zealand
 Norway
 Pakistan
 Philippines
 Poland
 Portugal
 Romania
 Singapore
 Slovakia
 Slovenia
 South Africa
 South Korea
 Spain
 Sweden
 Thailand
 United States
 Turkey
 United Arab Emirates
 United Kingdom
 Vietnam