
MoneyGram Exchange Rate and Tracking Guide: Costs, Delivery Time and Safer Alternatives




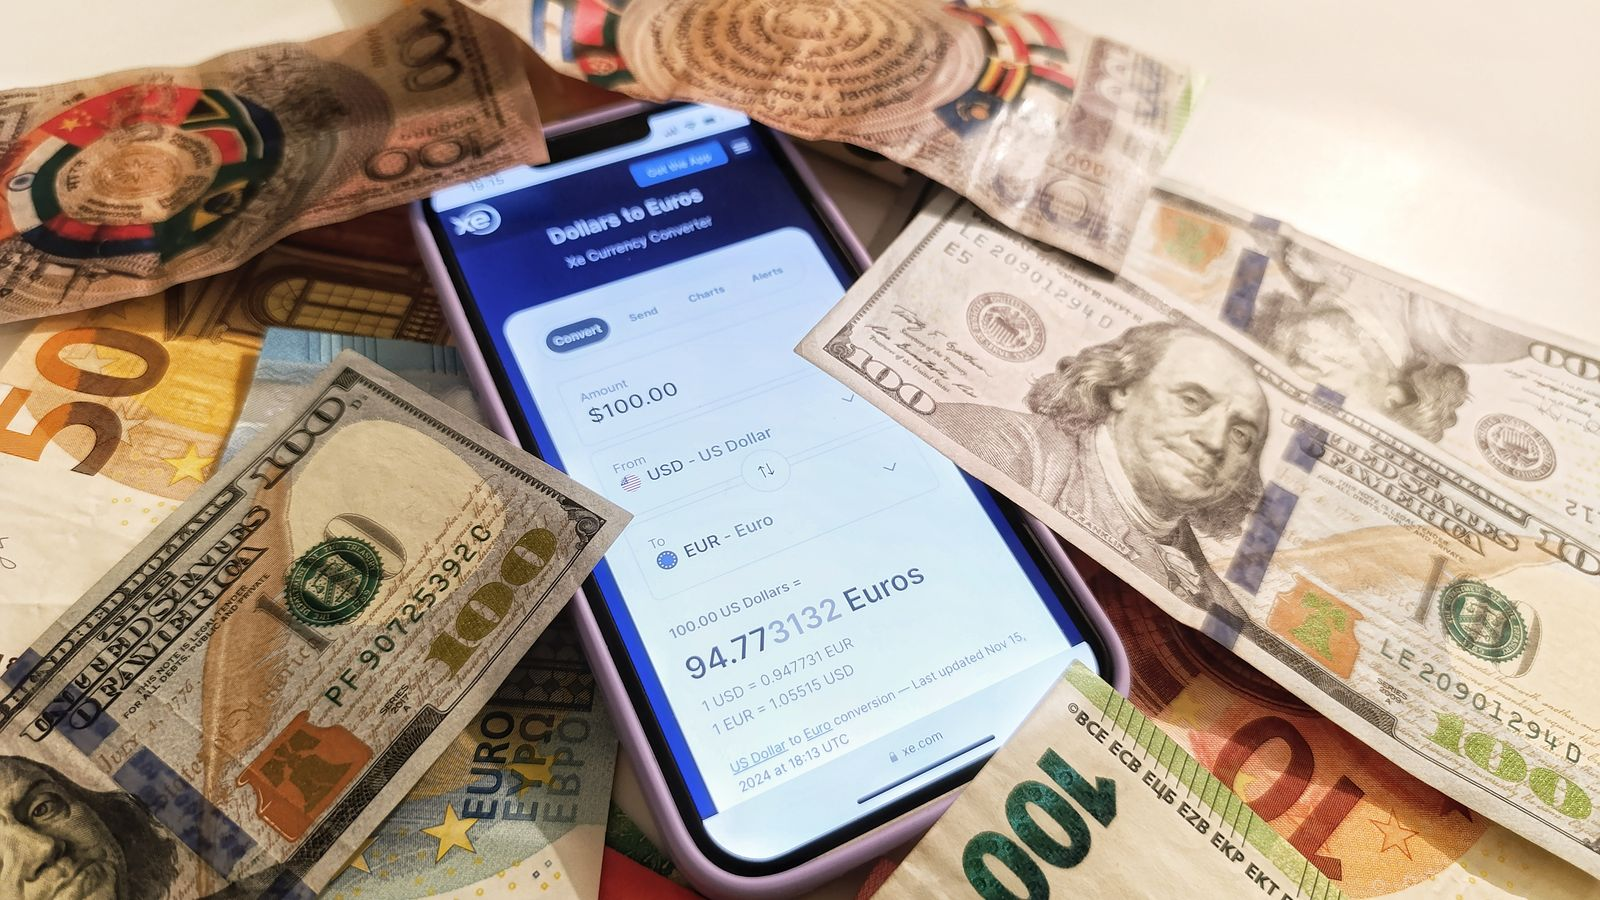
MoneyGram can be useful when you need to send money internationally, especially when the receiver needs cash pickup, bank deposit, debit card delivery, or mobile wallet access. The real question is not only “What is the MoneyGram exchange rate today?” but “How much will the receiver actually get after fees, exchange-rate differences, payment costs, and delivery conditions?” This guide helps you check the quoted rate, estimate the total transfer cost, track a MoneyGram transfer, understand delivery time, avoid common scam risks, and compare safer alternatives. Use it before confirming a transfer, when checking a pending payment, or when deciding whether MoneyGram, a bank transfer, Wise, Remitly, Western Union, WorldRemit, or a multi-currency tool fits your situation better.
Core Takeaways
- MoneyGram cost includes both the upfront transfer fee and the exchange-rate difference.
- Always compare the final recipient amount, not just the advertised fee or rate.
- Tracking usually depends on the reference number, sender details, and transaction history.
- Delivery speed depends on payout method, destination, verification, and local operating hours.
- Cash pickup can be fast, but transfers to strangers carry serious fraud and refund risks.
- Alternatives may work better for bank deposits, larger amounts, or clearer FX comparisons.
How MoneyGram Exchange Rates Work Before You Send Money
MoneyGram exchange rates are the rates used to convert your sending currency into the receiver’s payout currency. The key point is that the MoneyGram rate shown to you is not necessarily the same as the mid-market exchange rate you may see on Google, financial websites, or currency apps. MoneyGram’s own terms say the payout currency and exchange rate are reflected before payment and on the receipt, and any difference between the rate disclosed to you and the rate MoneyGram receives may be kept by MoneyGram or its agents. That makes the MoneyGram exchange rate part of the transfer cost, even when the upfront fee looks low.
MoneyGram exchange rate vs mid-market exchange rate
The mid-market rate is often used as a neutral benchmark because it sits between the buy and sell prices in the currency market. It is not always the exact rate a consumer gets from a remittance company, bank, card network, or cash exchange counter. Money transfer providers often build part of their cost into the exchange rate, which is why two services can show the same transfer fee but deliver different amounts to the receiver.
A practical example is simple. You send 1,000 USD to a receiver in another country. Provider A charges a $5 fee but uses a weaker exchange rate. Provider B charges a $10 fee but uses a better exchange rate. Provider B may still deliver more money. That is why the exchange-rate margin matters as much as the transfer fee.
What affects the MoneyGram rate you see
The rate you see can change by corridor, payout method, and timing. A “corridor” means the sending country, receiving country, and currency pair. For example, sending USD to MXN is different from sending SGD to PHP or GBP to INR. The rate can also differ when you send online, in the app, or through an agent location.
Before you confirm, check these inputs:
| Factor | Why it matters | What you should check |
|---|---|---|
| Sending country | Pricing and available methods vary by market | Confirm your local MoneyGram service options |
| Receiving country | Payout partners and currencies differ | Check cash pickup, bank deposit, wallet, or card delivery |
| Currency pair | Some currencies have wider FX spreads | Compare the quoted rate with a market benchmark |
| Payment method | Card, bank, and cash funding may price differently | Review fee and possible third-party charges |
| Receive method | Cash pickup and bank deposit may have different pricing | Compare final recipient amount |
| Transfer amount | Larger amounts can change fee tiers or checks | Confirm limits and verification requirements |
How to check the real recipient amount
The most useful number is the final amount your receiver gets. MoneyGram explains that the cost of sending money internationally usually depends on the transfer fee and exchange rate, along with destination and delivery method. In supported markets, MoneyGram also shows what the recipient receives before you confirm, which is the number you should use for comparison.
A clear checking process is:
- Enter your sending amount and destination.
- Select the receiver’s payout method.
- Review the transfer fee.
- Review the exchange rate.
- Check the final payout amount.
- Compare that payout amount with at least one alternative.
- Confirm only after the receiver name, payout method, and delivery estimate are correct.
You can also use a neutral FX reference such as a currency converter or a multi-currency tool. For example, Biya currency converter can help you form a quick rate reference before comparing the transfer quote shown by any provider. The reference rate is not a guarantee that a remittance platform will match it, but it helps you spot whether the delivered amount looks reasonable.
Summary: MoneyGram exchange rates should be read as part of the total transfer price, not as a standalone number. The rate shown during checkout is the rate that matters for your transaction, but it may include a margin compared with the mid-market rate. A low transfer fee does not automatically mean a low-cost transfer, because a weaker exchange rate can reduce the amount your receiver gets. The safest way to compare MoneyGram with other options is to enter the same send amount, destination, currency, payment method, and payout method, then compare the final delivered amount. If you only compare the transfer fee, you may miss the largest cost component. If you only compare the exchange rate, you may ignore card or bank charges. The best pre-send habit is to check fee, rate, payout amount, delivery estimate, and cancellation conditions before payment.
MoneyGram Fees, Hidden Costs, and Total Transfer Cost
The total cost of a MoneyGram transfer is usually bigger than the visible transfer fee. You should calculate it as upfront fee plus exchange-rate margin plus any possible card, bank, intermediary, or receiver-side charges. In the United States, remittance providers must generally give customers disclosures before payment, and the CFPB guide explains that a pre-payment disclosure can include the transfer amount, exchange rate, certain fees, taxes, and expected delivered amount. Outside the U.S., disclosure rules and cancellation rights can differ, so the practical rule is simple: use the checkout screen and receipt as your source of truth.
Transfer fee by payment and receive method
MoneyGram fees vary based on the amount, destination, payment method, delivery method, and pickup location. Paying by bank account may price differently from paying by debit card, credit card, cash, Apple Pay, or other local methods. Receiving by cash pickup may also differ from receiving into a bank account, debit card, or mobile wallet.
Common payment and receive combinations include:
| Payment method | Receive method | Typical cost issue | Practical check |
|---|---|---|---|
| Debit card | Cash pickup | Fast but may cost more than bank funding | Compare final payout and fee |
| Credit card | Cash pickup or bank deposit | Possible issuer cash advance fee | Check card issuer terms first |
| Bank account | Bank account | Often slower but may be cheaper | Check delivery estimate |
| Cash at agent | Cash pickup | Useful for unbanked users | Confirm agent hours and ID rules |
| Digital wallet funding | Mobile wallet | Convenient where supported | Check local wallet availability |
Exchange-rate margin as part of the total cost
An exchange-rate margin is the gap between a provider’s offered rate and a market reference rate. It is not always shown as a separate fee, but it affects the receiver’s payout. A transfer with “$0 fee” can still cost money if the exchange rate is less favorable.
Use this simple formula:
| Cost component | How it appears | Why it matters |
|---|---|---|
| Upfront transfer fee | Shown before payment | Direct sender-side cost |
| FX spread or margin | Built into exchange rate | Reduces receiver payout |
| Card issuer fee | Charged by your bank or card company | May appear outside MoneyGram |
| Intermediary or receiving charge | Charged by banks or local partners | May reduce delivered amount |
| Cancellation or refund cost | Depends on status and local rules | Affects recovery if plans change |
The cleanest comparison is not “Which provider has the lowest fee?” It is “Which provider delivers the most money to the receiver, within the time and payout method I need?”
Third-party charges and payment risks
Card issuer fees can be easy to miss. Some credit card issuers treat money transfers as cash advances, which can trigger fees and interest. Banks may also apply intermediary or receiver-side charges in some transfer routes. These charges are not always controlled by the remittance provider.
Before paying, ask:
- Is the payment method treated as a purchase or cash advance?
- Is the transfer funded by bank account, debit card, credit card, or cash?
- Will the receiver get cash, bank deposit, wallet balance, or debit card funds?
- Is the quoted payout guaranteed, estimated, or subject to local deductions?
- Does the receipt show the exchange rate and expected delivery amount?
If you regularly compare remittance costs, keep a record of quoted rate, fee, payment method, and actual received amount. Over several transfers, this gives you a realistic view of which corridor is cheaper for your use case.
Summary: MoneyGram fees should be evaluated as a total delivered-cost problem. The upfront fee is only one part of the cost. The exchange-rate margin, payment method, card issuer treatment, bank deductions, and receiver-side conditions can all change the real amount delivered. If the receiver needs cash quickly, paying a higher total cost may be acceptable. If the receiver has a bank account and timing is flexible, a bank-funded digital transfer or another provider may be better. The best comparison method is to enter the same amount and destination across several providers, write down the recipient amount, and check whether the payment method creates extra charges. You do not need to guess which service is cheaper; the checkout quote and final delivered amount usually give the most practical answer.
How to Track a MoneyGram Transfer Step by Step
To track a MoneyGram transfer, you usually need the transaction reference number and confirmation details. If you sent online or in the app, your transaction history may also show the latest status. MoneyGram says users can use the reference number and confirmation details to check transfer status online or in the app. Some country-specific tracking flows may ask for extra information, such as the sender’s last name, date of birth, or receiver name. Tracking helps you understand status, but it does not automatically solve delays caused by verification, banking schedules, or incorrect details.
Information needed to track a MoneyGram transfer
Keep the receipt or confirmation message until the transfer is complete. The most important tracking item is usually the reference number, sometimes called the 8-digit reference number for cash pickup. The receiver may need this number plus a valid government-issued photo ID when collecting cash.
Before tracking, collect:
| Item | Who usually has it | Why it matters |
|---|---|---|
| Reference number | Sender | Main tracking identifier |
| Sender’s legal name | Sender and support | Helps match transfer record |
| Receiver’s legal name | Sender and receiver | Must match ID or account details |
| Destination country | Sender | Helps support locate corridor |
| Payment method | Sender | Useful if payment review causes delay |
| Delivery method | Sender and receiver | Determines pickup or deposit flow |
| Receipt or confirmation email | Sender | Proof of transfer details |
Do not share the reference number publicly or with anyone who is not the intended receiver. For cash pickup, the reference number can be sensitive because it helps the receiver collect funds.
MoneyGram tracking status meanings
Status wording may vary by country, platform, or transaction type, but most statuses fall into a few practical categories.
| Status type | What it usually means | What you should do |
|---|---|---|
| Sent or submitted | Transfer was created | Wait for processing or review |
| Processing or in progress | Payment or compliance checks may still be active | Recheck later and confirm details |
| Available for pickup | Receiver may collect cash | Tell receiver the location, ID rules, and reference number |
| Delivered or completed | Funds were collected or deposited | Save receipt for records |
| On hold | More review or information may be needed | Contact support if status does not change |
| Canceled or refunded | Transfer did not complete | Check refund timing and fees |
MoneyGram notes that transfers may remain processing because of verification checks, payment method review, incorrect recipient information, or local banking schedules. That is why tracking should be paired with detail checking.
What to do if the transfer is delayed
A delayed transfer does not always mean the money is lost. Start with the simplest checks before contacting support:
- Confirm the receiver’s full legal name.
- Check whether the name matches the receiver’s ID or bank account.
- Confirm the destination country and payout currency.
- Confirm whether the receiver should use a specific agent location.
- Check local bank holidays and agent operating hours.
- Review whether your payment method was approved.
- Look for emails or app messages requesting additional information.
- Contact MoneyGram support if the status remains unchanged.
For bank deposits, small spelling errors, missing account details, or local bank review can create delays. For cash pickup, the receiver may also be limited by agent working hours, local compliance checks, available currency, or ID requirements.
Summary: MoneyGram tracking is most useful when you treat it as a status and detail-checking tool. The reference number is essential, but you should also keep the receipt, sender details, receiver name, payout method, and destination information. If the transfer is processing, first check whether the receiver’s name, payment method, delivery method, and local operating hours are correct. If the transfer is available for pickup, the receiver should bring a valid ID and the required reference number. If the status is on hold or delayed beyond the expected window, support may need more information. Tracking does not guarantee instant delivery, but it helps you identify whether the transfer is moving normally, waiting for review, ready for collection, completed, or canceled.
MoneyGram Delivery Time by Receive Method
MoneyGram delivery time depends mainly on the receive method, destination country, payment method, verification requirements, local bank schedules, and agent availability. Cash pickup is often the fastest route where supported, while bank deposits and wallet transfers can be instant, same day, next day, or longer depending on local partners. MoneyGram lists several receive methods, including cash pickup, bank account, debit card, home delivery, and mobile wallet, but availability varies by country. You should treat any delivery estimate as conditional until the transfer is paid, reviewed, and accepted by the payout partner.
Cash pickup delivery time
Cash pickup is usually chosen when the receiver does not have a bank account, needs emergency funds, or prefers in-person collection. It can be fast because the receiver may collect funds at a participating location once the transfer is available. However, “fast” still depends on the agent being open, local rules, ID match, reference number, and cash availability.
Cash pickup is often best when:
- The receiver needs physical cash.
- The receiver is unbanked or underbanked.
- A nearby MoneyGram agent is available.
- The sender trusts the receiver.
- The transfer amount is within local limits.
- The receiver can show valid ID.
It is less suitable when the receiver cannot reach an agent location, does not have matching ID, or is being pressured by someone else to receive and pass on money.
Bank deposit, debit card, and mobile wallet delivery time
Digital delivery can be more convenient when the receiver has a bank account, eligible debit card, or mobile wallet. It may also reduce the need for travel and cash handling. The trade-off is that banks and wallet partners may create processing delays, especially outside business hours or during verification.
| Receive method | Typical use case | Main delay factor |
|---|---|---|
| Cash pickup | Emergency funds or unbanked receiver | Agent hours, ID, cash availability |
| Bank deposit | Family support, bills, regular remittance | Bank processing and account details |
| Debit card | Quick access where supported | Card eligibility and country support |
| Mobile wallet | Mobile-first markets | Wallet partner and phone details |
| Home delivery | Select local markets | Local availability and address accuracy |
If the receiver needs funds by a specific date, do not rely only on the marketing phrase “in minutes.” Review the exact delivery estimate shown before payment and leave room for verification.
Why a MoneyGram transfer may be held or delayed
A transfer can slow down for several legitimate reasons. Payment review may happen when you use a card or bank account. Compliance checks may apply to certain amounts, corridors, or recipient patterns. Local banks may not process transfers outside business hours. Agent locations may be closed even if the transfer is technically ready.
Common delay reasons include:
- Incorrect receiver name or account information.
- Sender payment method not approved.
- Extra identity verification.
- Compliance or fraud review.
- Bank holiday or weekend processing.
- Local partner outage.
- Receiver ID mismatch.
- Destination-specific payout restrictions.
You can reduce delays by entering the receiver’s full legal name exactly as shown on ID or bank records, choosing a payout method the receiver can use, and confirming all details before payment.
Summary: MoneyGram delivery time is not one fixed number. Cash pickup can be the fastest option when the receiver has valid ID and access to a nearby agent, but it also depends on local operating hours and compliance rules. Bank deposits, debit card delivery, and mobile wallet transfers can be convenient, but they depend on partner systems, banking schedules, and correct account details. The most reliable way to estimate speed is to check the delivery quote during the transaction setup, then read the receipt after payment. If timing is critical, choose a receive method with the fewest external dependencies and avoid sending at the last minute before weekends or holidays. Speed should be compared together with total cost, payout access, and fraud risk.
MoneyGram Safety, Refunds, and Scam Risks
MoneyGram can be safe for sending money to people you know and trust, but it is risky when the receiver is a stranger, online seller, fake employer, romance contact, prize organizer, or anyone pressuring you to act quickly. The FTC warns that wiring money through services like MoneyGram, Ria, or Western Union can be like sending cash, and you should not wire money to anyone you haven’t met in person. Once cash is picked up or funds are deposited, recovery may be difficult or unavailable. Safety depends less on the brand name and more on recipient trust, transaction purpose, and whether the transfer can still be stopped.
When MoneyGram is suitable and when it is risky
MoneyGram is commonly used for family support, emergency assistance, gifts, education expenses, and other legitimate cross-border needs. It can be suitable when you know the receiver, understand why the money is being sent, and can verify their identity independently.
It becomes risky when any of these warning signs appear:
| Warning sign | Why it is dangerous |
|---|---|
| Someone says you won a prize but must pay first | Common advance-fee scam pattern |
| A stranger asks for urgent cash pickup | Money may be hard to recover |
| A seller only accepts wire transfer | You may lose buyer protection |
| A caller claims to be a government agency | Real agencies usually do not demand wire transfers |
| Someone asks you to keep the transfer secret | Pressure and secrecy are fraud signals |
| A romance contact asks for emergency money | Identity may be fake |
| A job offer requires you to send funds onward | Could involve fraud or money mule risk |
If any warning sign appears, stop and verify through a separate trusted channel. Do not use a phone number or link provided by the person requesting money.
Refund and cancellation basics
Cancellation depends on transfer status and local rules. MoneyGram states in one regional example that a transfer cannot be canceled if the receiver has already collected the funds or the funds have already been deposited, and its cancellation wording also distinguishes between earlier and later cancellation timing. Rules can vary by country, payment method, and legal framework, so always check the rule that applies to your sending market.
In the U.S., certain remittance transfers may carry cancellation and error-resolution rights, including a limited 30 minutes to cancel in covered cases if conditions are met. That protection should not be assumed globally. For international users, the practical rule is: if you suspect a mistake or fraud, act immediately.
Steps to take quickly:
- Open transaction history or receipt.
- Check whether cancellation is available.
- Contact MoneyGram support if the transfer is not collected.
- Contact your bank or card issuer if payment details are compromised.
- Report suspected fraud to local authorities or consumer protection bodies.
- Keep all receipts, messages, and names.
Fraud prevention checklist
Before sending, ask yourself:
- Do I personally know the receiver?
- Can I verify the request outside the current conversation?
- Is anyone rushing me?
- Is someone asking me to lie about the purpose?
- Is the payment for a prize, tax, visa, rental, job, romance, or online sale?
- Would I still send if the money could not be recovered?
If the answer raises doubt, do not send. A legitimate receiver can usually wait while you verify details.
Summary: MoneyGram is a legitimate money transfer service, but no transfer method removes the need for sender caution. The highest-risk transfers are usually not family remittances; they are urgent payments to strangers, online sellers, fake officials, romance contacts, or people who pressure you to keep the transfer secret. Refunds and cancellation rights depend on timing, transfer status, local rules, and whether funds have already been collected or deposited. Once money has been paid out, recovery can be difficult. The safest habit is to verify the receiver, confirm the purpose, avoid pressure, keep documentation, and stop immediately if the transaction involves secrecy, urgency, or an unfamiliar recipient.
Safer Alternatives to MoneyGram and How to Choose
A safer alternative to MoneyGram is not always the cheapest app. It is the provider that fits your corridor, payout method, urgency, compliance needs, transparency expectations, and receiver access. MoneyGram may be suitable when cash pickup is essential, especially in markets with strong agent coverage. Digital-first alternatives may be better when the receiver can accept bank deposit or wallet delivery and you want clearer exchange-rate comparison. Wise explains the mid-market rate as a benchmark for comparing currency conversion, while other services such as Remitly, Western Union, and WorldRemit may compete on speed, cash coverage, or delivery methods.
When MoneyGram may still be the right choice
MoneyGram can be a strong fit when the receiver needs physical cash, lives near an agent, or cannot easily receive bank transfers. It can also be practical when the sender wants online, app, and in-person options in one service.
Use MoneyGram when:
- The receiver needs cash pickup.
- The transfer is urgent and the corridor supports fast payout.
- The receiver lacks a bank account.
- The local agent network is convenient.
- You can verify the receiver personally.
- The final delivered amount is acceptable after comparison.
Do not choose MoneyGram only because the visible fee appears low. Always compare the exchange rate and final payout.
When digital alternatives may work better
Digital providers may be better for users who care about rate transparency, bank deposits, or larger planned transfers. Wise pricing emphasizes upfront fees and currency conversion transparency, while Remitly exchange rates can be checked by corridor before sending. Western Union may be worth comparing when broad agent coverage matters, and WorldRemit is relevant when mobile money, airtime top-up, bank transfer, or cash pickup options are available in the receiver’s country.
A decision table can help:
| User need | MoneyGram fit | Alternative type to compare | Main caution |
|---|---|---|---|
| Emergency cash pickup | Strong where agents are nearby | Western Union, cash pickup providers | Fraud and ID rules |
| Bank-to-bank support | Depends on corridor | Wise, banks, Remitly | Speed and limits |
| Transparent FX comparison | Requires rate comparison | Wise, currency tools | Final payout still matters |
| Mobile wallet payout | Corridor-specific | WorldRemit, Remitly | Wallet availability |
| Larger planned transfer | May need checks | Bank, Wise, specialist FX provider | Verification and limits |
| Ongoing multi-currency use | Not only remittance | Multi-currency wallet | Product availability |
Decision framework for MoneyGram vs alternatives
Compare providers with the same transfer setup. Do not compare a card-funded cash pickup with a bank-funded bank deposit and call one “cheaper” without noting the difference.
Use this five-step comparison:
- Select the same send amount and destination.
- Choose the receiver’s real payout method.
- Record the transfer fee and exchange rate.
- Record the final amount the receiver gets.
- Check delivery time, cancellation terms, and identity requirements.
If you also manage cross-border payments, currency conversion, and transaction records beyond one-off remittances, a multi-currency workflow may help. For example, Biya money transfer can be considered when you need to review cross-border payment routes, while the Biya app may be relevant for users who want payment records and global financial tools in one place. Product availability, fees, and eligibility should always be checked in the app and local rules.
Summary: MoneyGram is not automatically better or worse than alternatives. It is strongest when the receiver needs cash and can access a participating location. It may be less attractive when you are sending to a bank account, comparing larger transfers, or prioritizing transparent FX pricing. Wise, Remitly, Western Union, WorldRemit, banks, and multi-currency platforms each solve different problems. The best method is to compare the final recipient amount, speed, payout method, support options, refund conditions, and compliance requirements. If you send money regularly, keep a simple record of each provider’s quoted rate, fee, delivery time, and actual received amount. Over time, that record is more useful than relying on generic claims about the cheapest provider.
After you compare MoneyGram exchange rates, transfer fees, and delivery options, you may still need a broader way to manage cross-border payment records, currency conversion references, and global financial activity. That is where a multi-asset wallet workflow can be useful. Biya is positioned as a global multi-asset trading wallet, and its payment scenarios can be relevant when you need to manage cross-border transfers, online spending, and currency-related records in one place.
For payment and online spending needs, BiyaPay EasyCard can support global online subscriptions, AI service payments, billing records, and payment process management. For users who also follow markets, the Biya trading workspace covers U.S. stocks, Hong Kong stocks, and digital assets, which is a different scenario from remittance but may sit in the same broader global-finance workflow. Biya also supports USDT conversion into major fiat currencies such as USD or HKD, and it covers payments across 190+ countries and regions with more than 40 local currencies.
If you use Biya for investment-related activity, note that U.S. stock trading commission is listed as $0; the platform fee is $0.005 per share, with a minimum of $0.99 per order and a maximum of 1% of trade value. External agency and trading activity fees are listed as $0.00396 per share. Fractional-share orders below one share are charged a platform fee of 1% of trade value, capped at $1. Fees, product availability, eligibility, order pages, and local regulatory requirements should be checked before use.
FAQ
Does MoneyGram use the mid-market exchange rate for international transfers?
MoneyGram does not have to use the mid-market rate as your customer exchange rate. It shows a transfer exchange rate before confirmation, and that rate may include a margin. You should compare MoneyGram’s quoted rate with a market benchmark and focus on the final recipient amount after fees.
How can you calculate the total cost of a MoneyGram international transfer?
Calculate MoneyGram’s total transfer cost by adding the upfront transfer fee, the exchange-rate difference, and any possible bank, card, or third-party charges. The most practical comparison is the final amount your receiver gets, because a low fee can be offset by a weaker exchange rate.
Why is a MoneyGram transfer still pending after the estimated delivery time?
A MoneyGram transfer may stay pending because of verification checks, payment review, incorrect recipient details, local banking schedules, agent operating hours, or compliance requirements. Check the reference number, receiver name, payout method, and support messages before assuming the transfer has failed.
Can you cancel a MoneyGram transfer after sending money internationally?
You may be able to cancel a MoneyGram transfer only if the transfer status and local rules allow it. Once the receiver has collected cash or funds have been deposited, cancellation is usually much harder or unavailable. Check your transaction history, receipt, and local MoneyGram rules immediately.
Is MoneyGram safer than online money transfer alternatives for cash pickup?
MoneyGram can be safe for cash pickup when you send to someone you know and the receiver has valid ID. It is not automatically safer than digital alternatives. Safety depends on recipient trust, fraud checks, refund options, transaction status, and whether the money has already been collected.
When should you compare MoneyGram with Wise, Remitly, Western Union, or bank transfers?
You should compare MoneyGram with other providers when you care about final payout, exchange-rate transparency, cash pickup access, delivery time, transfer limits, or refund conditions. For bank deposits or larger planned transfers, digital providers or banks may offer a better fit, depending on corridor and fees.
*Ang artikulong ito ay ibinigay para sa pangkalahatang layunin ng impormasyon at hindi bumubuo ng legal, buwis, o iba pang propesyonal na payo mula sa BiyaPay o sa mga subsidiary at kaakibat nito, at hindi ito nilalayong maging kapalit ng pagkuha ng payo mula sa isang financial advisor o sinumang iba pang propesyonal.
Hindi kami gumagawa ng anumang pahayag o garantiya, hayag man o ipinahiwatig, hinggil sa katumpakan, kabuuan, o pagiging napapanahon ng nilalaman ng publikasyong ito.
Mga kaugnay na blog tungkol sa

Choosing a Stock Trading App: Beginner Checklist


Crypto-Related Stocks vs Digital Assets: What Investors Actually Own


Estrategiya ng MACD Crypto Trading: Mga Setting, Senyales, at Pamamahala sa Panganib

Wire Transfer Requirements: Sender and Beneficiary Details Checklist
Pumili ng Bansa o Rehiyon para Basahin ang Lokal na Blog
 Australia
 Austria
 Belhika
 Canada
 Siprus
 Republika ng Tsek
 Dinamarka
 Estonia
 Pinlandiya
 Pransiya
 Alemanya
 Gresya
 Hong Kong
 India
 Indonesia
 Ireland
 Italya
 Hapon
 Latvia
 Lithuania
 Luxembourg
 Malaysia
 Malta
 Morocco
 Nepal
 Olanda
 New Zealand
 Noruwega
 Pakistan
 Pilipinas
 Poland
 Portugal
 Romania
 Singapore
 Slovakia
 Eslobenya
 Timog Aprika
 Timog Korea
 Espanya
 Suwesya
 Taylandiya
 Estados Unidos
 Turkiya
 Nagkakaisang Arabong Emirato
 Nagkakaisang Kaharian
 Biyetnam